Partnership taxation can seem complicated because a partnership is both a business entity and a tax-reporting system. The partnership files an annual federal tax return, but it usually does not pay federal income tax itself. Instead, it reports income, deductions, gains, losses, and other tax items to its partners.
Each partner then reports the allocated items on that partner’s own tax return.
This guide explains the basic federal tax rules for partnerships in the United States. It also covers partnership tax returns, common deductions, pass-through taxation, and the important difference between inside basis and outside basis.
This article provides general educational information. Partnership tax rules are highly technical, and a tax professional should review significant transactions, ownership changes, debt allocations, distributions, and sales of partnership interests.
Partnership Tax Return
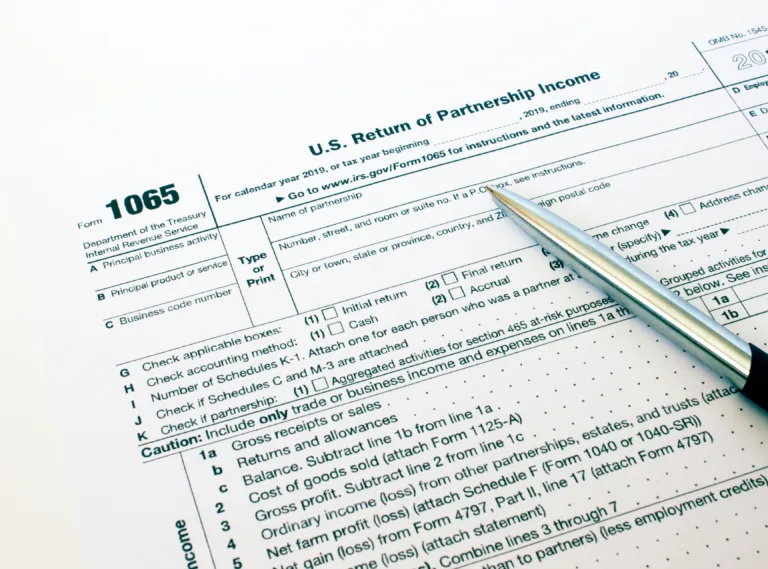
Most domestic partnerships file Form 1065, U.S. Return of Partnership Income, with the Internal Revenue Service. Form 1065 is generally an informational return. It tells the IRS how much income the partnership earned, what deductions it claimed, and how it allocated tax items among the partners.
A partnership commonly includes two or more people or entities that carry on a business or investment activity and share its profits and losses. A limited partnership, limited liability partnership, and multi-member LLC taxed as a partnership generally follow the federal partnership tax rules.
The partnership reports its ordinary business income or loss on Form 1065. It also separately states certain items that may receive different tax treatment at the partner level. These separate items can include:
- Interest income
- Dividend income
- Capital gains and losses
- Section 1231 gains and losses
- Charitable contributions
- Foreign tax items
- Tax-exempt income
- Depreciation-related deductions
- Credits and credit-related information
The partnership provides each partner with a Schedule K-1. The K-1 reports that partner’s share of the partnership’s tax items. A partner uses the K-1 to prepare the partner’s federal income tax return.
For a calendar-year partnership, Form 1065 is generally due on March 15. A partnership may generally obtain an automatic six-month extension by timely filing Form 7004. The extension extends the time to file, not necessarily the time to make any required payments at the partner level.
Partnership agreements matter. They often specify how the partnership allocates profits, losses, distributions, and other items among the partners. However, the tax allocation must satisfy federal tax rules. An allocation generally needs substantial economic effect, or it must otherwise reflect the partners’ interests in the partnership.
What Deductions are available on a Partnership Tax Return
A partnership may generally deduct ordinary and necessary expenses paid or incurred in carrying on its trade or business. The deduction reduces partnership taxable income, which in turn reduces the taxable income allocated to the partners.
Common deductible business expenses may include:
- Employee wages and benefits
- Rent for office, retail, warehouse, or other business space
- Utilities, internet, telephone, and software costs
- Advertising and marketing expenses
- Professional fees, including legal, accounting, and consulting fees
- Business insurance
- Office supplies and equipment
- Repairs and maintenance
- Business travel expenses
- Interest expense, subject to applicable limitations
- Depreciation and amortization
- State and local taxes that are deductible at the entity level
- Certain retirement-plan contributions
A partnership can generally deduct depreciation over time for qualifying business assets. For example, the partnership may depreciate machinery, furniture, computers, vehicles, and certain improvements to business property. The applicable recovery period and method depend on the asset and the relevant tax rules.
Some expenses are not currently deductible, even if they relate to the business. A partnership may need to capitalize certain costs rather than deduct them immediately. Capitalized costs become part of the basis of an asset and may be recovered through depreciation, amortization, or a deduction upon sale.
The partnership also cannot deduct personal expenses. It may not deduct federal income taxes. Fines, penalties, and certain lobbying expenses may also be nondeductible. Meals are subject to special limitations, and entertainment expenses are generally not deductible.
Partners should also remember that a deduction at the partnership level does not always mean that every partner can use the deduction immediately. A partner’s ability to deduct allocated losses may depend on outside basis, at-risk limitations, passive activity loss rules, and other restrictions.
Do Partnerships Pay Any Taxes
A partnership usually does not pay federal income tax on its taxable income. Instead, it operates as a pass-through entity for federal income-tax purposes.
The partnership calculates its taxable income and separately stated items. It then allocates those items to the partners. Each partner generally reports the allocated income or loss, whether or not the partnership actually distributes cash to that partner.
For example, assume a partnership earns $200,000 of ordinary taxable income. If two equal partners each receive a 50 percent allocation, each partner generally reports $100,000 of partnership income on that partner’s own tax return. This result can apply even if the partnership retains all of the cash for business operations.
That distinction is important. A partner may owe tax on allocated income without receiving a cash distribution to pay the tax. For that reason, many partnership agreements provide for tax distributions. A tax distribution is a distribution intended to help partners pay taxes attributable to partnership income.
Although partnerships generally do not pay federal income tax, they may still have other tax obligations. Depending on the business and location, a partnership may need to pay or remit:
- Payroll taxes
- Employment taxes
- Sales and use taxes
- Excise taxes
- State or local franchise taxes
- State-level entity taxes
- Withholding taxes for foreign partners or nonresident partners
- Estimated taxes in certain situations
Some states also impose entity-level taxes or elective pass-through entity taxes. Those rules vary by jurisdiction and can materially affect the partners’ tax results.
What’s the Difference between Inside Basis and Outside Basis
Inside basis and outside basis are fundamental partnership tax concepts. The terms sound similar, but they describe different tax bases.
Inside basis is the partnership’s adjusted tax basis in its individual assets. For example, if a partnership buys a building for $1 million, the partnership initially has a $1 million inside basis in that building. Depreciation, capital improvements, and other tax adjustments change that basis over time.
The partnership uses inside basis to determine depreciation, amortization, and gain or loss when it sells an asset. If the partnership sells an asset, it generally compares the sales price with its inside basis in that asset.
Outside basis is a particular partner’s adjusted tax basis in that partner’s partnership interest. A partner’s outside basis generally starts with the money contributed and the adjusted basis of property contributed. It then changes over time.
Outside basis generally increases for:
- Additional capital contributions
- The partner’s share of partnership taxable income
- The partner’s share of tax-exempt income
- Increases in the partner’s share of partnership liabilities
Outside basis generally decreases for:
- Cash and property distributions
- The partner’s share of deductible losses and expenses
- Nondeductible partnership expenses
- Decreases in the partner’s share of partnership liabilities
Outside basis matters because it affects whether a partner may deduct allocated partnership losses. It also affects the tax result when the partner receives distributions or sells the partnership interest.
A cash distribution usually reduces the recipient partner’s outside basis. A partner generally recognizes gain if cash distributed exceeds the partner’s outside basis immediately before the distribution.
The difference between inside and outside basis becomes especially important when a partnership interest is sold, inherited, gifted, or transferred. It can also matter after certain distributions. In appropriate cases, a Section 754 election may permit basis adjustments that help align the partnership’s inside basis with a transferee partner’s outside basis.
Sample Calculation of Inside and Outside Basis
Assume that Alex and Blair form AB Partnership. Each contributes $100,000 in cash. The partnership uses the $200,000 to buy equipment.
At formation:
| Item | Alex | Blair | Partnership |
|---|---|---|---|
| Cash contribution | $100,000 | $100,000 | $200,000 |
| Outside basis | $100,000 | $100,000 | N/A |
| Inside basis in equipment | N/A | N/A | $200,000 |
The partnership owns equipment with an initial inside basis of $200,000. Each partner has an outside basis of $100,000 in the partnership interest.
During the first year, the partnership earns $60,000 of ordinary taxable income before considering depreciation. It claims $20,000 of depreciation on the equipment. The partnership therefore has $40,000 of ordinary taxable income.
Assume the partnership allocates all items equally.
Each partner receives:
- $20,000 of ordinary taxable income
- $10,000 of depreciation deduction as part of the calculation of partnership income
- No cash distribution during the year
The partnership’s equipment basis changes as follows:
$200,000 initial inside basis−$20,000 depreciation=$180,000 adjusted inside basis
Each partner’s outside basis changes as follows:
$100,000 initial outside basis+$20,000 allocated income=$120,000 ending outside basis
Now assume the partnership distributes $30,000 of cash to each partner. Each partner’s outside basis is reduced:
$120,000 outside basis before distribution−$30,000 cash distribution=$90,000 ending outside basis
The cash distribution generally does not produce taxable gain because each partner’s $30,000 distribution does not exceed that partner’s $120,000 outside basis before the distribution.
Later, if the partnership sells the equipment for $220,000, it compares the sales price with its $180,000 inside basis:
$220,000 sale price−$180,000 inside basis=$40,000 partnership gain
The partnership allocates the $40,000 gain between Alex and Blair under the partnership agreement and applicable tax rules. If allocated equally, each partner generally reports $20,000 of gain and increases outside basis accordingly.
Conclusion
Partnership tax planning requires attention to both the entity-level asset basis and the partner-level interest basis. Keeping accurate capital accounts, tax-basis records, liability allocations, and distribution records can prevent costly errors and make future planning far easier.